
A real estate NPL is a loan or credit facility that is in default and linked to a real estate asset, typically used as collateral for the debt. NPL stands for Non-Performing Loan, a term used to describe loans that are no longer performing in accordance with their original repayment terms.
For investors, investing in real estate NPLs provides exposure to distressed debt through a fundamentally different approach from traditional property investment: the investor does not initially acquire the property itself, but rather a credit claim that may be backed by real estate collateral.
The potential of these transactions lies in acquiring the credit position under specific conditions and subsequently implementing a recovery strategy. However, assessing an NPL requires a thorough understanding of the debt, the collateral, the legal situation, the expected timeline and the different potential recovery scenarios.
What is a real estate NPL?
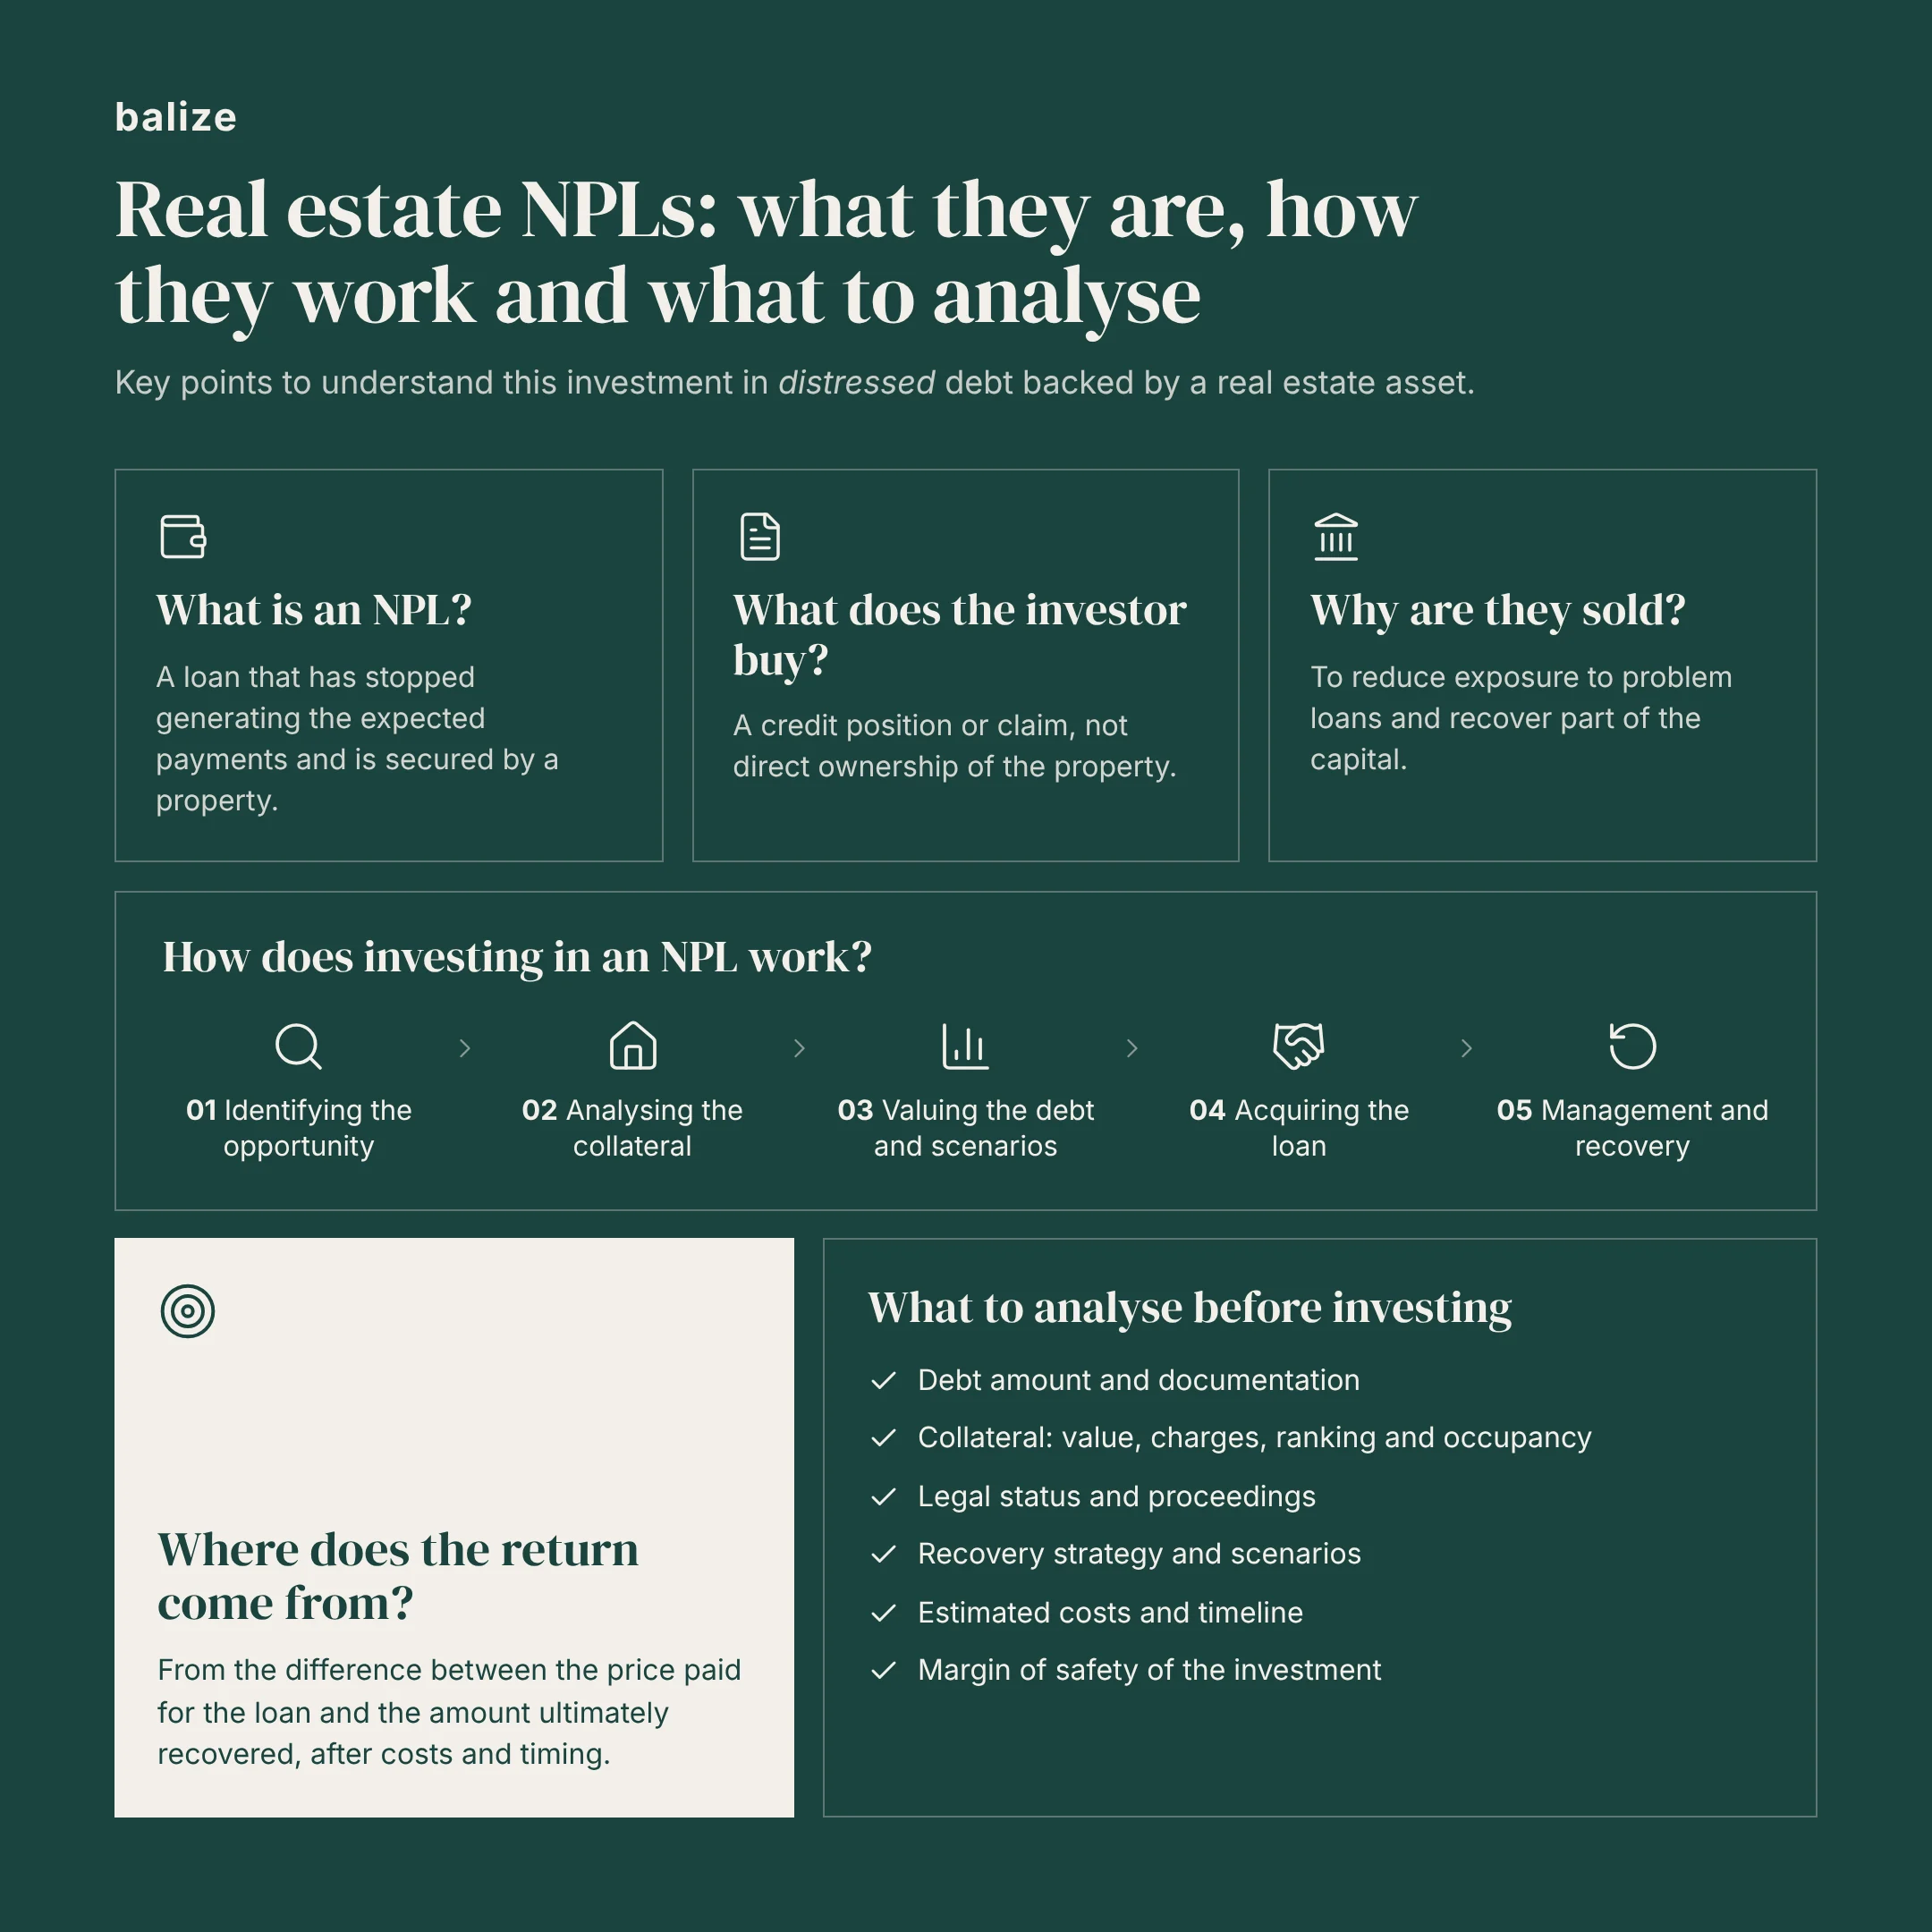
A real estate NPL is a loan that is no longer generating the expected repayments and whose debt is linked to or secured by a real estate asset.
NPL stands for Non-Performing Loan. In the financial sector, the term is used to identify loans where the borrower has stopped meeting their payment obligations or where circumstances indicate that full recovery under the original terms may be unlikely.
When the loan is secured by a mortgage, the underlying property becomes particularly relevant because it may provide collateral supporting the creditor's claim.
For this reason, when analysing a real estate NPL, two distinct but closely related elements need to be assessed:
This dual dimension distinguishes real estate debt investment from the conventional acquisition of a property.
What does an investor actually acquire when investing in an NPL?
When investing in a real estate NPL, the investor does not directly acquire the property: they acquire a credit position or claim against a debtor.
This distinction is fundamental to understanding how NPL investing works.
If the loan is secured by a mortgage, a real estate asset supports the debt, but acquiring the loan does not automatically make the investor the owner of the property.
Following the acquisition, different recovery routes may be available depending on the transaction, the debtor's circumstances and the applicable legal proceedings.
For this reason, assessing only the property's market value without analysing the underlying credit position would be insufficient. The debt documentation, encumbrances, ranking of the security, existing proceedings and expected timelines may be just as important as the property itself.
Why are real estate NPLs sold?
Financial institutions and other creditors may sell NPL portfolios or individual positions to reduce their exposure to problematic loans, recover part of their capital and manage their balance sheets.
When a loan stops performing as expected, managing it may require specialist resources, time and recovery proceedings.
In certain circumstances, the creditor may prefer to transfer the credit position to a third party rather than continue managing the entire recovery process directly.
For the buyer, this can create an opportunity if the acquisition price of the debt allows for a recovery strategy with an appropriate balance between potential return and risk.
However, acquiring a loan at a discount to its nominal value does not automatically make it an attractive investment. Investors need to assess how much can realistically be recovered, how long the process may take and what costs may be required.
How does a real estate NPL investment work?
A real estate NPL investment typically begins with the analysis and acquisition of the credit claim, followed by a strategy aimed at recovering capital through a negotiated solution, debt recovery or enforcement of the collateral, as applicable.
In simplified terms, the process can be divided into several stages:
1. Identifying the opportunity
A non-performing loan or portfolio of loans is identified and its main characteristics are assessed, including the outstanding debt, documentation, collateral, borrower and legal situation.
2. Analysing the underlying collateral
Where real estate collateral exists, the underlying property is assessed in terms of location, market value, condition, encumbrances, land registry and occupancy status, and potential exit scenarios.
3. Valuing the debt and recovery scenarios
The investor estimates how much may be recovered, through which routes, within what timeframe and at what cost.
At this stage, it is particularly important to model different scenarios rather than relying solely on the most favourable outcome.
4. Acquiring the credit position
If the transaction meets the established investment criteria, the acquisition of the credit position is completed under the negotiated terms.
5. Management and recovery
Once the credit position has been acquired, the management phase begins. Depending on the circumstances of each case, different resolution strategies may be considered, always subject to the legal and contractual position of the transaction.
How are returns generated when investing in NPLs?
Returns from an NPL investment may arise from the difference between the price paid to acquire the credit position and the value ultimately recovered, after accounting for the costs and time required to execute the strategy.
This means that the nominal value of the debt should not be confused with the actual return on the investment.
For example, if a credit position is acquired for less than the amount ultimately recovered, an economic margin may exist. However, calculating the actual return requires taking into account:
For this reason, timing is particularly important when assessing the return of a real estate NPL. Two investments generating the same absolute profit may produce very different annualised returns if one takes considerably longer to resolve.
To better understand how investment returns are measured, our guide to gross return, net return and IRR in real estate investment explains the main metrics used to assess an investment.
What role does real estate collateral play in an NPL?
Real estate collateral can be one of the main forms of security supporting an NPL, but its existence does not eliminate investment risk.
The analysis must determine not only the potential value of the property, but also the legal position of the credit claim in relation to that collateral and the circumstances that could affect recovery.
Among other factors, investors should consider:
A high property valuation does not, by itself, guarantee that this amount can be recovered or that recovery will take place within the expected timeframe.
NPL vs REO: what is the difference?
The main difference between an NPL and an REO is that an NPL initially represents an investment in debt, whereas an REO is a real estate asset that has already become the property of a financial institution or creditor following a recovery process.
Although both concepts belong to the distressed real estate universe, they represent different situations.
Understanding this distinction helps avoid one of the most common misconceptions: assuming that acquiring distressed debt and directly acquiring a real estate asset are equivalent transactions.
Are NPLs and assignments of the winning bid the same?
No. An NPL and an assignment of the winning bid are different legal and investment structures that arise at different stages within the distressed real estate process.
With an NPL, the investor acquires a credit position linked to non-performing debt. An assignment of the winning bid, by contrast, relates to enforcement proceedings in which the party entitled to the award of the property may transfer that right to a third party, provided the relevant legal requirements are met.
Our guide to what an assignment of the winning bid is and how it works explains this structure and its main characteristics in greater detail.
What are the risks of investing in real estate NPLs?
Investing in real estate NPLs can create opportunities, but it also involves specific risks related to debt recovery, collateral valuation, legal proceedings, costs and timelines.
The main risks include:
These factors make thorough analysis particularly important. In our article on the risks of real estate investment, we explain how to assess some of these variables within an investment strategy.
What should an investor analyse before investing in an NPL?
Before investing in an NPL, investors should assess the quality of the credit, the real estate collateral, the legal situation, the acquisition price and the potential recovery scenarios as a whole.
Some of the main questions to consider include:
As with other real estate investment strategies, the analysis should not be limited to the return projected under the base-case scenario. Investors should also assess what happens when the main assumptions change. In our guide on how to assess the financial fundamentals of a real estate investment opportunity, we examine other relevant factors to consider before making an investment decision.
How are NPLs related to distressed real estate?
Real estate NPLs form part of the distressed real estate universe, which includes investments linked to assets, credit positions or real estate situations involving some form of financial, legal or execution-related difficulty.
This universe can include a range of opportunities and structures, such as NPL debt, REO assets, property auctions, assignments of winning bids and other special situations.
They do not all work in the same way or carry the same risk profile. It is therefore essential to understand what is being acquired, where the transaction sits within the recovery process and where the expected return is intended to come from.
Why do NPLs require specialist management?
NPL investing requires financial, real estate and legal expertise because the outcome depends both on the acquisition of the credit position and on the subsequent recovery strategy.
Unlike a conventional real estate investment, where the analysis may focus primarily on the asset and its operation or disposal, an NPL also requires a detailed understanding of the credit documentation, collateral and potential recovery proceedings.
The ability to analyse all these elements correctly can be critical in determining whether the acquisition price provides an appropriate margin of safety for the investment.
How does NPL investment fit within balize?
At balize, we analyse real estate opportunities across different strategies, including transactions within the distressed real estate universe, before presenting them to our private investors' club.
For these types of investments, assessing the opportunity requires an understanding not only of the underlying real estate asset, but also of the transaction structure, legal situation, potential resolution scenarios, costs and investment horizon.
The objective is to assess each opportunity from a comprehensive perspective and understand where the potential for value creation comes from and what risks must be assumed in seeking to achieve it.
Frequently asked questions about real estate NPLs
What does NPL mean in real estate?
NPL stands for Non-Performing Loan and refers to a loan experiencing repayment problems. In a real estate context, it typically refers to debt linked to or secured by a real estate asset.
When you buy an NPL, do you also buy the property?
No. Acquiring an NPL initially means acquiring a credit claim, not directly purchasing the property. Where mortgage security exists, the property supports the debt, but ownership of the asset is not automatically transferred when the credit position is acquired.
How do investors make money from NPLs?
The potential return may arise from the difference between the acquisition cost of the credit position and the value ultimately recovered, after deducting all necessary costs and taking into account the time required to execute the strategy.
What is the difference between an NPL and an REO?
With an NPL, the investor acquires a debt position that remains subject to recovery. An REO is a property that has already become the asset of a financial institution or creditor following a previous recovery or foreclosure process.
Are real estate NPLs risky?
Yes. NPL investing involves risks related to debt recovery, the value and status of the collateral, costs, legal proceedings, timelines and liquidity, among other factors.
Conclusion
A real estate NPL provides a way to gain exposure to the real estate market through debt rather than necessarily through the direct acquisition of a property.
It follows a different investment logic: acquiring a credit position, analysing the collateral supporting it and implementing a recovery strategy whose outcome may depend on multiple financial, real estate and legal variables.
For this reason, before investing in NPLs, it is essential to understand exactly what is being acquired, the value and status of the collateral, the available resolution scenarios and the potential costs and timelines associated with each one.
At balize, we analyse and select real estate investment opportunities before presenting them to our private investors' club. If you would like to explore the opportunities currently available, you can request access to balize's private investors' club.
*All investments involve risk. Investing in NPLs and distressed debt may involve financial, real estate, legal, liquidity, valuation, recovery and timing risks. The existence of real estate collateral does not guarantee the recovery of invested capital or any particular level of return. Actual results, costs and timelines may differ from initial estimates. This content is provided for informational purposes only and does not constitute financial, tax, legal or investment advice.